The practice

One desk, thirty-one lenders, and no house product to push

I spent two years at a bank learning that the answer to a complicated file is almost always no when there is only one rulebook. Then I stopped working at a bank.

Why a broker, and why only Richmond

A bank loan officer sells one price sheet and one set of guidelines. When your file fits, that is perfectly fine and often cheap. When it does not, there is nowhere for the file to go, and the conversation ends with a decline letter that explains very little.

A broker has somewhere to put it. The same documents, the same single credit pull, submitted to whichever wholesale desk has guidelines that fit and pricing that works this week. In practice that difference shows up most on self-employed files, on jumbo purchases in the West End and Goochland, and on anything with a story attached.

Richmond only, because a mortgage is a local business pretending to be a national one. The appraiser knows which blocks in Church Hill are comparable. The settlement agent knows the county recordation quirks. The listing agent has seen my pre-approval letters before and knows what they mean. None of that transfers.

The file declined on Tuesday was approved on Thursday, with the same documents.

What moving to wholesale in 2016 actually taught me
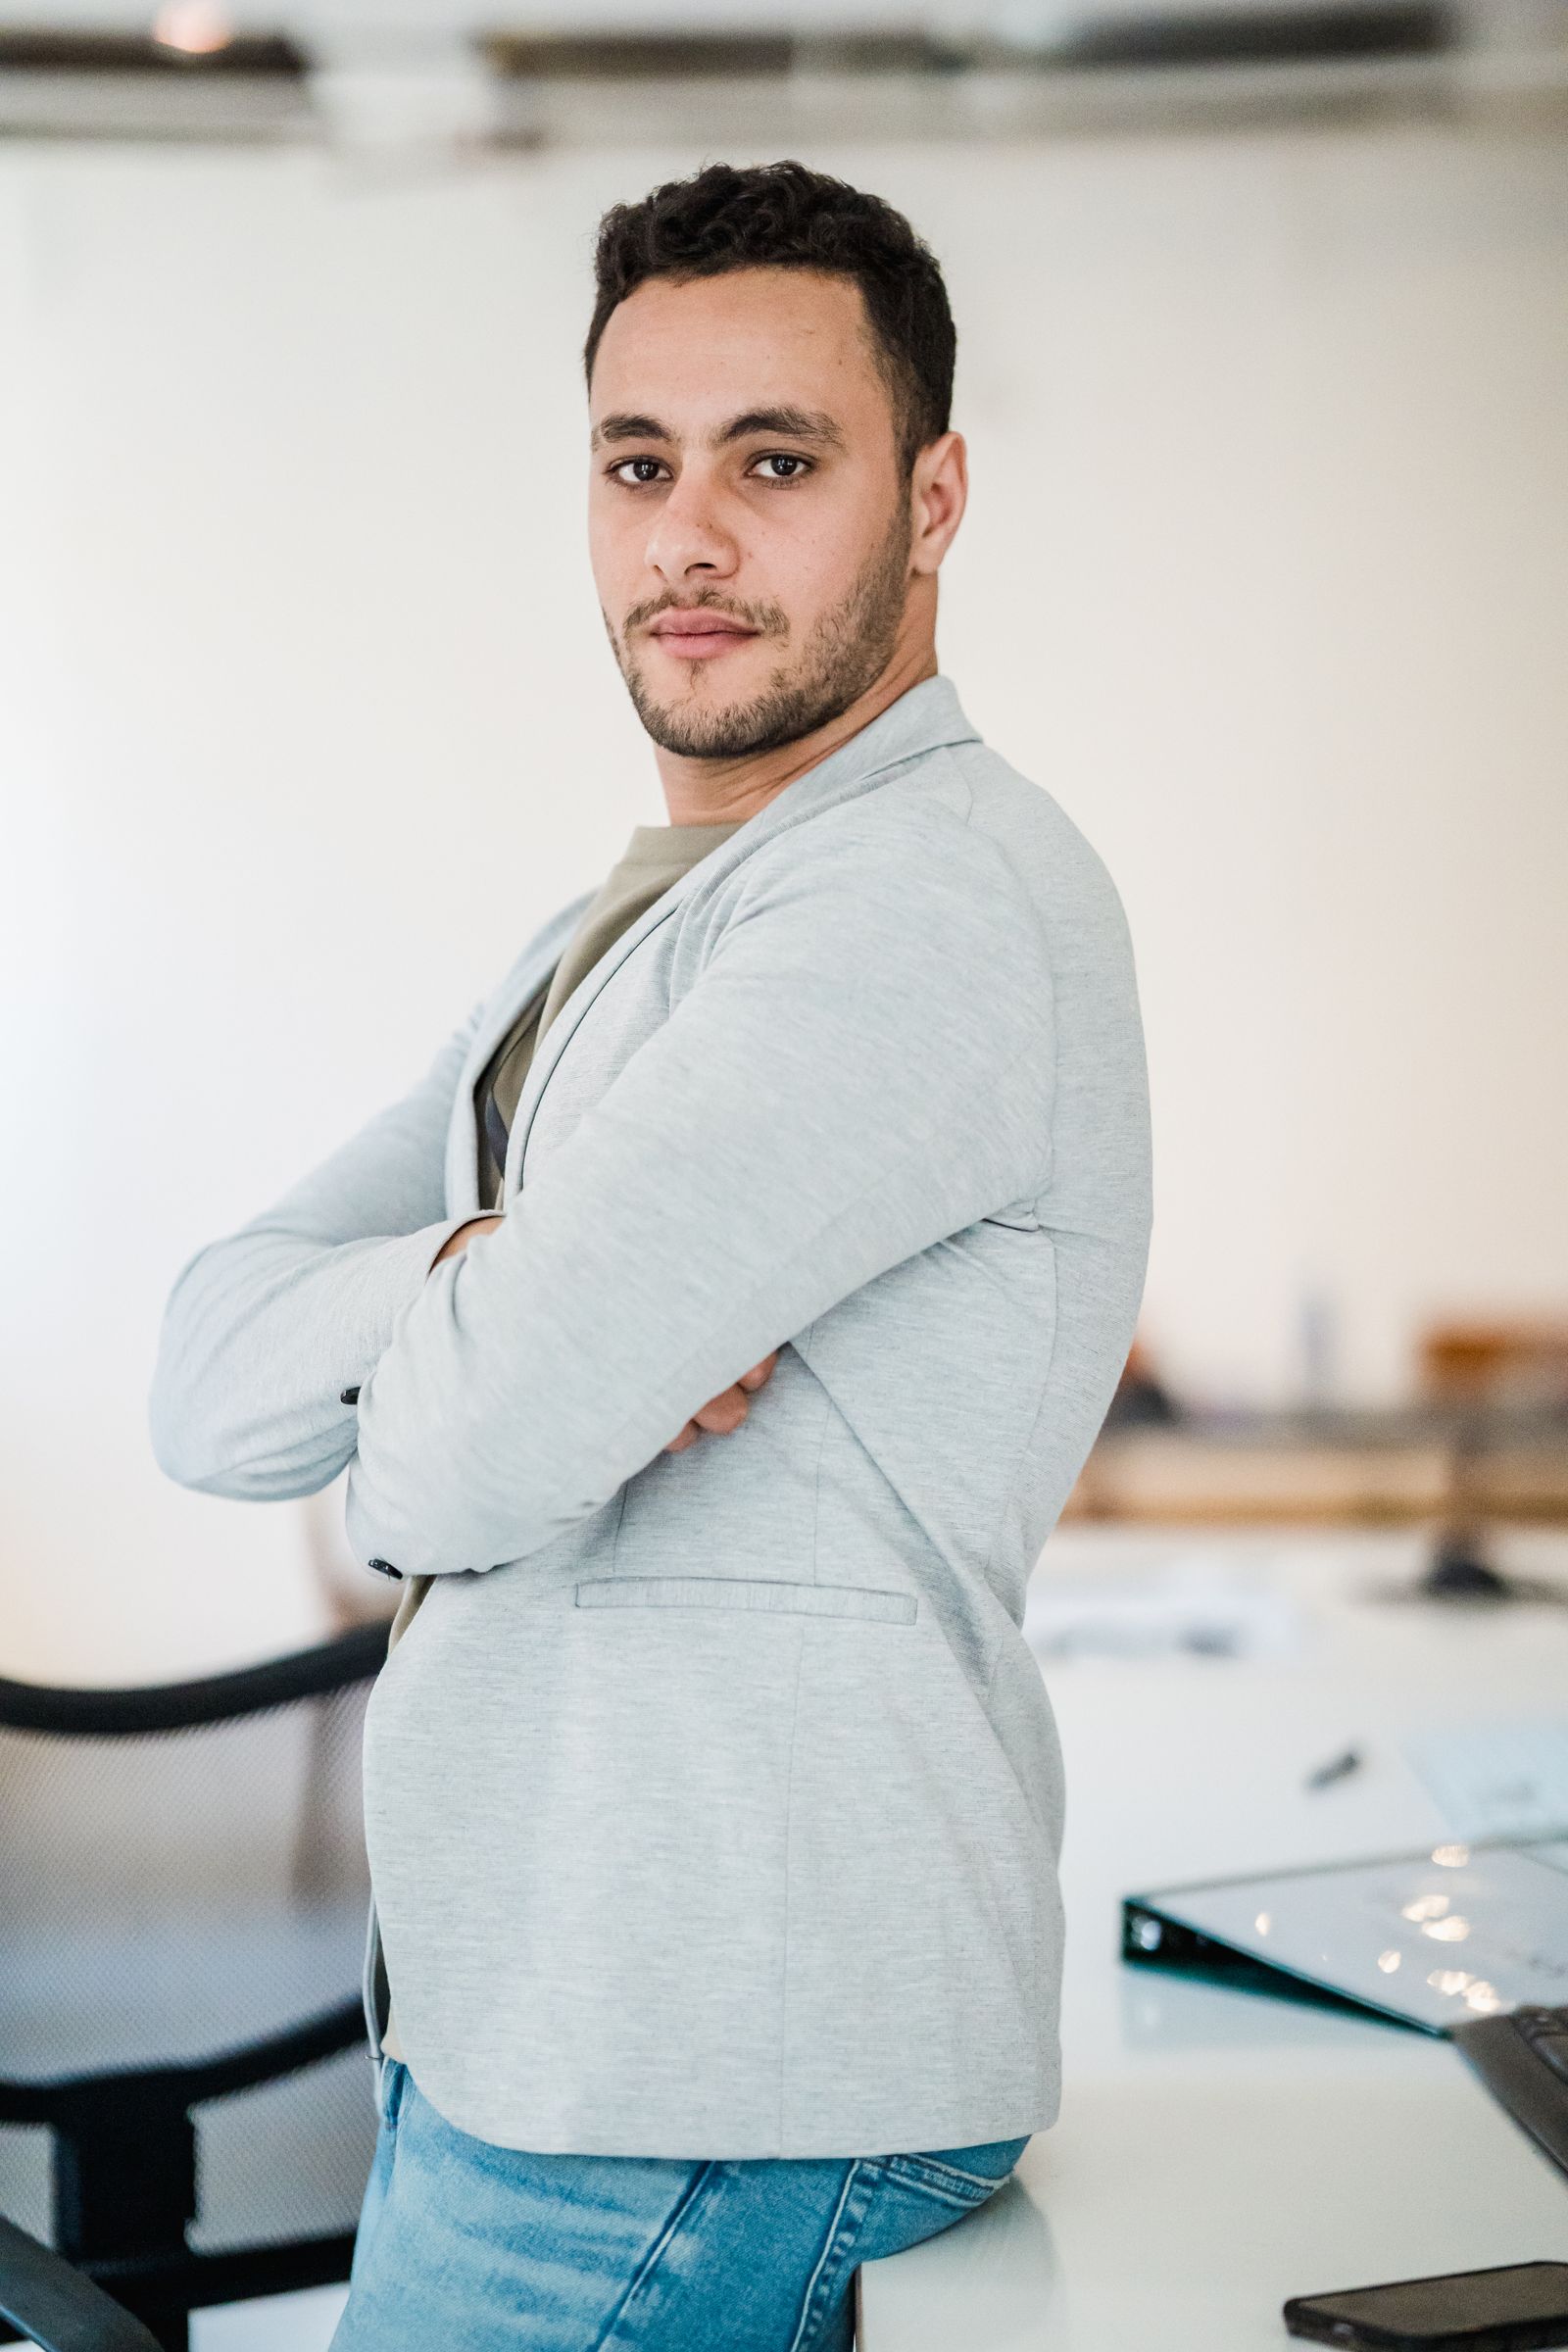
Jordan Hayes at the East Main Street officeJordan Hayes · NMLS #XXXXXXX
Richmond, Virginia. Licensed in Virginia, Maryland and North Carolina.

How I work

Four rules I will not bend

  • Show the working

    Every recommendation arrives with the arithmetic attached. Three wholesale quotes on the same day's pricing, a five-year net cost for each, and the reason I would pick one. If you disagree with the reasoning, you can see it to disagree with.

  • Say no out loud

    Roughly one call in six ends with me saying the move does not pay yet. A refinance with a 41-month break-even for someone moving in two years is a loss dressed as a saving. I would rather lose the file than write that one.

  • Twice a week, regardless

    Tuesday and Friday updates from application to closing, whether or not anything changed. Silence is the single thing borrowers complain about most, and it costs nothing to fix.

  • One pull, one file

    Credit is pulled once. That one report goes to every desk on the panel. Multiple mortgage enquiries inside 45 days count as one event for scoring, so shopping properly costs your score nothing.

The record, in four numbers

Figures from my own pipeline. Sample data for this demonstration site.

  • 1,240Richmond-area loans closed since 2014Sample
  • 22 daysMedian contract to clear-to-close, last 12 monthsSample
  • 31Wholesale lenders on the panelSample
  • 96%Files that closed on or before the contract dateSample

Twelve years

How the practice got here

  1. 2014

    Retail loan officer, downtown Richmond

    Two years at a depository bank, learning that the answer to a hard file was almost always no, because there was only one rulebook to consult.

  2. 2016

    Moved to wholesale

    Joined a brokerage and discovered that the file declined on Tuesday was approved on Thursday at a different desk with the same documents.

  3. 2019

    Licensed in Maryland and North Carolina

    Clients moving out of the region kept asking. Two more state licences, and the same panel of lenders.

  4. 2022

    Opened on East Main Street

    A one-person practice with a wholesale panel behind it. No sales floor, no call queue, no house product to push.

  5. 2026

    Thirty-one lenders on the panel

    Reviewed quarterly. A desk that misses turn times twice comes off, whatever the pricing looks like.

Credentials

Licences and what they mean

  • NMLS #XXXXXXXIndividual mortgage loan originator
  • Virginia MLO licenceBureau of Financial Institutions
  • Maryland and North CarolinaLicensed in three states
  • Equal Housing OpportunityFair lending, every file
  • 8 hours continuing educationCompleted annually, SAFE Act
  • Independent brokerage31 wholesale lenders, no house product

NMLS #XXXXXXX is a placeholder on this demonstration website. The real number belongs to the licensed originator, appears on every disclosure, and can be checked on the NMLS Consumer Access register. Full licensing detail.

Clients

What people actually say afterwards

4.9

592%
46%
31%
21%
10%

From 187 reviews Sample

  • Jordan sent three lender quotes side by side with the five-year cost worked out. Nobody else did that. We picked the second cheapest because it closed faster.

    Danielle OkonkwoChurch Hill · Conventional purchase
  • We thought assistance was free money. He showed us the rate premium over ten years and we still chose it, but at least we chose it knowing.

    Marcus and Thea WhitfieldMidlothian · Virginia Housing DPA
  • Two lenders told me my tax returns killed the deal. Jordan ran the add-backs, found $9,000 of depreciation and got me approved on full documentation.

    Reuben CastellanosScott's Addition · Self-employed, bank statement
  • The reserve requirement at our first bank was eighteen months. Jordan found a desk that wanted six. Same rate, completely different file.

    Priyanka NairShort Pump · Jumbo purchase

Read all 187 reviews

Twenty-five minutes, no credit pull

Tell me the goal, the timeline and roughly what the credit looks like. You will leave the call knowing what you qualify for and what it costs.

Three wholesale quotes on the same day's pricing, before you choose.

Cookie preferences

Choose which cookies you allow. You can change this at any time from the link in the footer.